Expanding to the US? What European founders should prepare first (Sponsored)

The question of expanding to the US often comes up early, while the team is still raising seed capital and still arguing about product-market fit at home. What makes it expensive is rarely the answer. It is the order. Customers, founder presence, immigration, fundraising, structure, banking and the evidence file all wait on each other.
1. Decide your timing before the market decides it for you
The case for starting earlier is in the data. Index Ventures’ research, published as “Winning in the US” and drawn from an analysis of over 500 VC-backed startups plus a survey of 140 companies, reports that 64% of companies now expand to the US at pre-seed or seed stage, against 33% across 2015–2019.
The longer series is the more interesting number: close to 60% expanded before a Series A between 2008 and 2014, so the current figure is a return to older behaviour rather than a straight line upwards.
Either way, preparing earlier is not the same as committing earlier, and international expansion is one of the few decisions where that difference costs real money. Both directions carry a cost: too early burns the runway and splits the founders’ attention, too late hands the market to whoever moves first.
The test to watch is repeatability. One enthusiastic buyer in Boston is a lead. Four buyers with the same problem, similar procurement patterns and a clear willingness to pay are a much stronger signal of repeatable demand.
Give the pilots a full quarter before hiring a sales leader, because two enterprise conversations in six weeks tell you very little about the sales cycle, and American enthusiasm in early meetings is easy to mistake for buying intent. A full quarter of pilot data gives a much better basis for separating what genuinely has to be local from what can stay in Europe.
2. Plan for founder presence: it matters more than most teams expect
US expansion usually becomes founder-led before it becomes headcount-led. Enterprise buyers want the person who can change the roadmap. Investors want to read the founder rather than the deck. First hires need someone to sit next to. None of that amounts to relocation. What it amounts to is knowing which activities need a body in the room, how often, and for how long.
So build the 90-day founder calendar before committing to a move to the US. Plot the customer meetings, the investor roadshow and the hiring work, then hold that calendar against the founder’s current immigration position. Some of it will fit. Some of it will need different authorisation, and that is the part worth discovering in March rather than in September, if you plan your trip in September.
3. Treat immigration as a business dependency, not end-stage paperwork
This is a work-stream that is often treated as paperwork and dealt with late, even though it can carry one of the longest lead times. It helps to know what the main founder route actually asks for.
O-1A covers extraordinary ability in the sciences, education, business or athletics, shown by sustained national or international acclaim. The petition needs either a major internationally recognised award or at least three of eight evidentiary criteria, among them recognised prizes, published material about the founder, judging the work of others, original contributions of major significance, a critical role for a distinguished organisation, and high remuneration.
Meeting three criteria is only the starting point, not the outcome. USCIS reads the record as a whole, so three well-documented criteria usually carry more weight than five weak ones.
Depending on the facts, counsel may also raise L-1, E-2, EB-2 NIW (national interest waiver) or the International Entrepreneur Rule. They are not interchangeable, and two of them can be ruled out before anyone examines merit. E-2 requires the founder’s nationality to be covered by a qualifying treaty, so it is not a universal founder option.
The International Entrepreneur Rule grants parole rather than a formal immigration status, which puts it in a different legal category from the visa classifications listed alongside it. EB-2 NIW is a permanent-residence route on a different timeline altogether. USCIS maintains an overview page, Options for Noncitizen Entrepreneurs to Work in the United States, covering the main routes.
Index Ventures, writing about founders preparing a US landing team, advises getting the visa process moving swiftly, planning for six months from application to verdict, involving lawyers early and keeping contingency plans for delays or rejections.
Under the regulations, an O petition may not be filed more than one year before the beneficiary’s services are actually needed, and USCIS advises filing at least 45 days before the start date to avoid delays. What happens after filing depends on the classification, whether premium processing is used, the agency’s workload and whether a request for evidence arrives.
Founder-owned companies need particular care with structure. USCIS policy guidance issued on 8 January 2025 confirms that an O-1 beneficiary cannot petition as an individual, but that a separate legal entity owned by the beneficiary, a corporation or an LLC, may file the petition on their behalf. Ownership is not disqualifying. Nor is it sufficient.
The company filing the petition must still document the terms and conditions of the proposed employment and its relationship with the founder: the regulations call for copies of any written contract between petitioner and beneficiary, or a summary of the terms where the agreement is oral.
In a founder-owned structure, that may also require showing that someone other than the beneficiary has authority over employment decisions. Whether that structure fits a particular case is a question for a qualified immigration attorney.
4. What US investors will ask, and what you should already know
US fundraising exposes organisational gaps quickly, and the questions arrive in a fairly predictable order: who owns the company, who owns the IP, who the customers actually are, how the data is secured, where the founder will physically be, and which entity the money would land in.
Not all of it has to be solved before the first meeting. What does have to be clear is which answers are settled and which are still opinions, because the distance between those two is precisely what diligence is built to find.
5. Set up incorporation, banking, taxes and employment as one connected decision
A Delaware C-corp is the default for VC-backed Tech companies, and default is not the same as correct for every foreign founder. The structure decides governance, tax, payroll, who signs contracts and how the European and US entities deal with each other, which is why it belongs with corporate and tax advisers before anything is filed.
Banking has its own sequence, and it is slower than most founders expect. The SelectUSA Investor Guide, published by the US Department of Commerce, gives a whole chapter to what foreign companies need in order to open a US bank account, which is a fair indication that this is not a formality added after incorporation. Many downstream steps depend on the EIN, including bank onboarding, payroll and payment processing. Two conditions determine whether the online application is available at all.
The IRS online application is open only where the entity has a legal residence, principal place of business or principal office in the United States or a US territory, and where the responsible party holds a valid SSN, ITIN or EIN. Fail either test and three alternative routes remain, and the Form SS-4 instructions attach very different numbers to them.
The international phone line can assign the number during the call, but only for applicants with no US residence, place of business or office. Fax comes back generally within four business days, provided you supply a return fax number. For post, the IRS advises allowing four to five weeks. Defaulting to post costs a month for no reason, and bank onboarding requirements still vary by institution afterwards.
Before anyone files, map the investor, IP, employment and tax relationships between the European parent and any US entity, and do it with advisers who can see all four at once.
6. Adapt your sales motion: the US market is not one market
Most of a European pitch survives the flight. The assumptions underneath it often do not. “Selling in America” is not a go-to-market plan: a Midwest manufacturer and a New York FinTech share a currency and not much else. Start narrow. One B2B buyer profile, one industry or region, and written hypotheses about deal size, cycle length and the proof the buyer will demand before signing.
A founder with two FinTech customers already has a sample worth learning everything from before hiring a generalist national sales team.
Contracts need localising too. Enterprise buyers bring their own procurement, privacy, security, insurance and indemnity requirements, and employment rules change from state to state. A European template should not be assumed to cover any of it.
7. Start documenting evidence early
The evidence file has two readers who want different things. Investors want proof that the company is working. Counsel wants proof that the founder personally stands out, which the company’s metrics do not show. That second test belongs to the routes built on a founder’s own record, O-1A included.
Others work differently: L-1 depends on corporate records and the role the founder held abroad, and E-2 depends on the source of the investment funds. Where both readers matter, the documents overlap but neither accepts the other’s version.
Start the file now, because it cannot be built backwards. Keep the dated originals: customer and revenue records, product adoption numbers, independent press rather than your own blog, award criteria as well as the award itself, judging invitations, and anything evidencing a critical role or a measurable outcome. Dates and provenance are what make the file usable, and an undated screenshot is close to worthless.
The point is narrower than building a visa profile. It is about not losing useful third-party evidence in an old inbox.
Practical takeaway: build the expansion plan before the move becomes urgent
Keep the plan conditional. Do the reversible work early: customer discovery, evidence capture, choosing advisers, mapping roles. Delay the expensive commitments until the market, the financing or the hiring case pays for them. The order matters more than the pace.
When should a European founder start US immigration planning? Before sustained US work or a relocation date becomes fixed. For evidence-heavy cases, an early inventory tends to reveal gaps that are difficult to close under a financing or customer deadline. The right lead time depends on the founder and the pathway, so current USCIS timing and counsel advice should set the calendar.
Do founders need a US entity before applying for a visa? Not as a universal rule. Different classifications carry different petitioner, employer, ownership and business-structure requirements. For O-1A, the petition must be filed by a qualifying petitioner, such as an employer, a US agent, or a separate company owned by the founder. Forming an entity does not by itself give the founder immigration status or work authorisation.
Is the O-1A suitable for startup founders? Sometimes, but being a founder by itself carries no weight. The O-1A looks at what a person has done and how well it is documented. A founder with independent press coverage, a critical role at a respected organisation, pay clearly above the norm for the field, or invitations to judge other people’s work may have a case. A founder with none of that on record does not have one yet. USCIS weighs the whole record rather than counting criteria, and the petitioner structure has to work as well, so both questions belong with counsel.
What should founders document before US fundraising? A clean cap table, IP records, customer and revenue evidence, contracts, security and compliance materials, hiring plans and a documented founder track record. The exact diligence list depends on the business and the investor, but clean source documents remove most of the avoidable scrambling.
Sources: Index Ventures, Winning in the US (2025); USCIS Policy Manual, Volume 2, Part M, and Options for Noncitizen Entrepreneurs to Work in the United States; US Department of State, Treaty Countries; Internal Revenue Service, Instructions for Form SS-4 (rev. December 2025); SelectUSA Investor Guide, US Department of Commerce.
This article is for general informational purposes only and does not constitute legal or tax advice. Rules, guidance and figures cited are current as of publication in September 2026 and are subject to change. Immigration, tax, corporate, employment and regulatory decisions should be reviewed with appropriately qualified advisers based on the specific facts and current law.
Related Stories
 Startups
What U.S. Investors Actually Look for During IP Due Diligence in African Startups
7 hours ago
 Startups
10 European funding vehicles dedicated to women founders
1 day ago
 Startups
‘The choice was prison or exile’: journalists who fled Russia publish grim portrait of Putin
1 day ago
 Startups
The companies that were never fundable are now buildable
1 day ago
 Startups
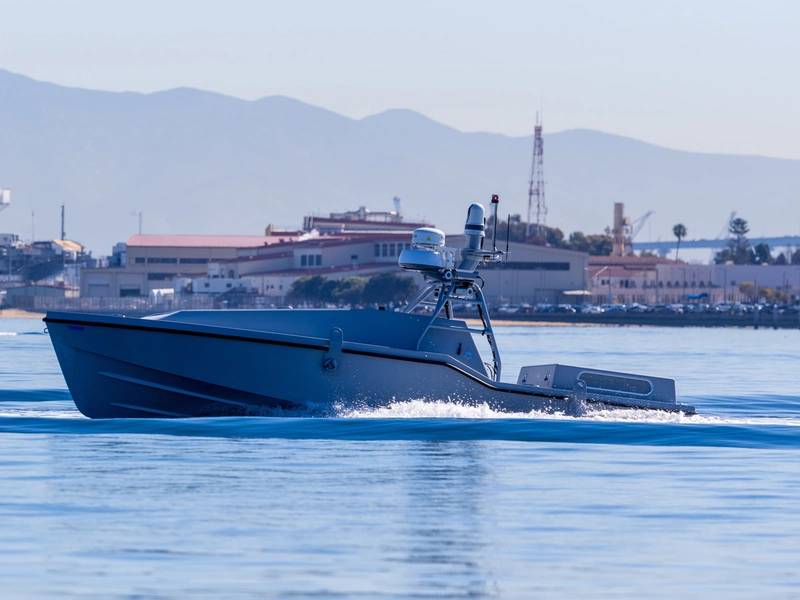
Saudi Defense Fund Steps Up Maritime Investment After Houthi Advance
1 day ago
 Startups
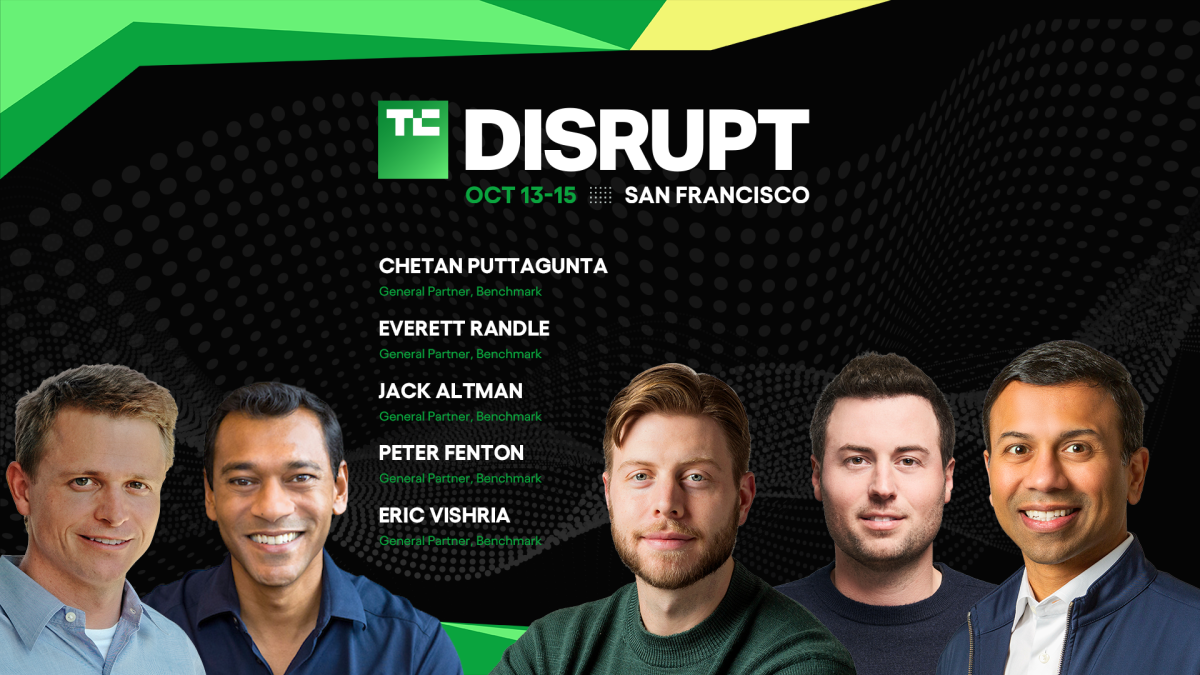
Benchmark’s full partnership joins the main stage at Disrupt 2026
1 day ago
 Startups
AVC launches its first pilots and integrations, with 300+ startups in 3 months
1 day ago
 Startups
Belgium’s NewSchool VC closes maiden fund at €10 million to back B2B technology startups
2 days ago