NRI nominee can inherit your money, but can they take it abroad? Know the FEMA rules
NRI nominee can inherit your money, but can they take it abroad? Know the FEMA rules
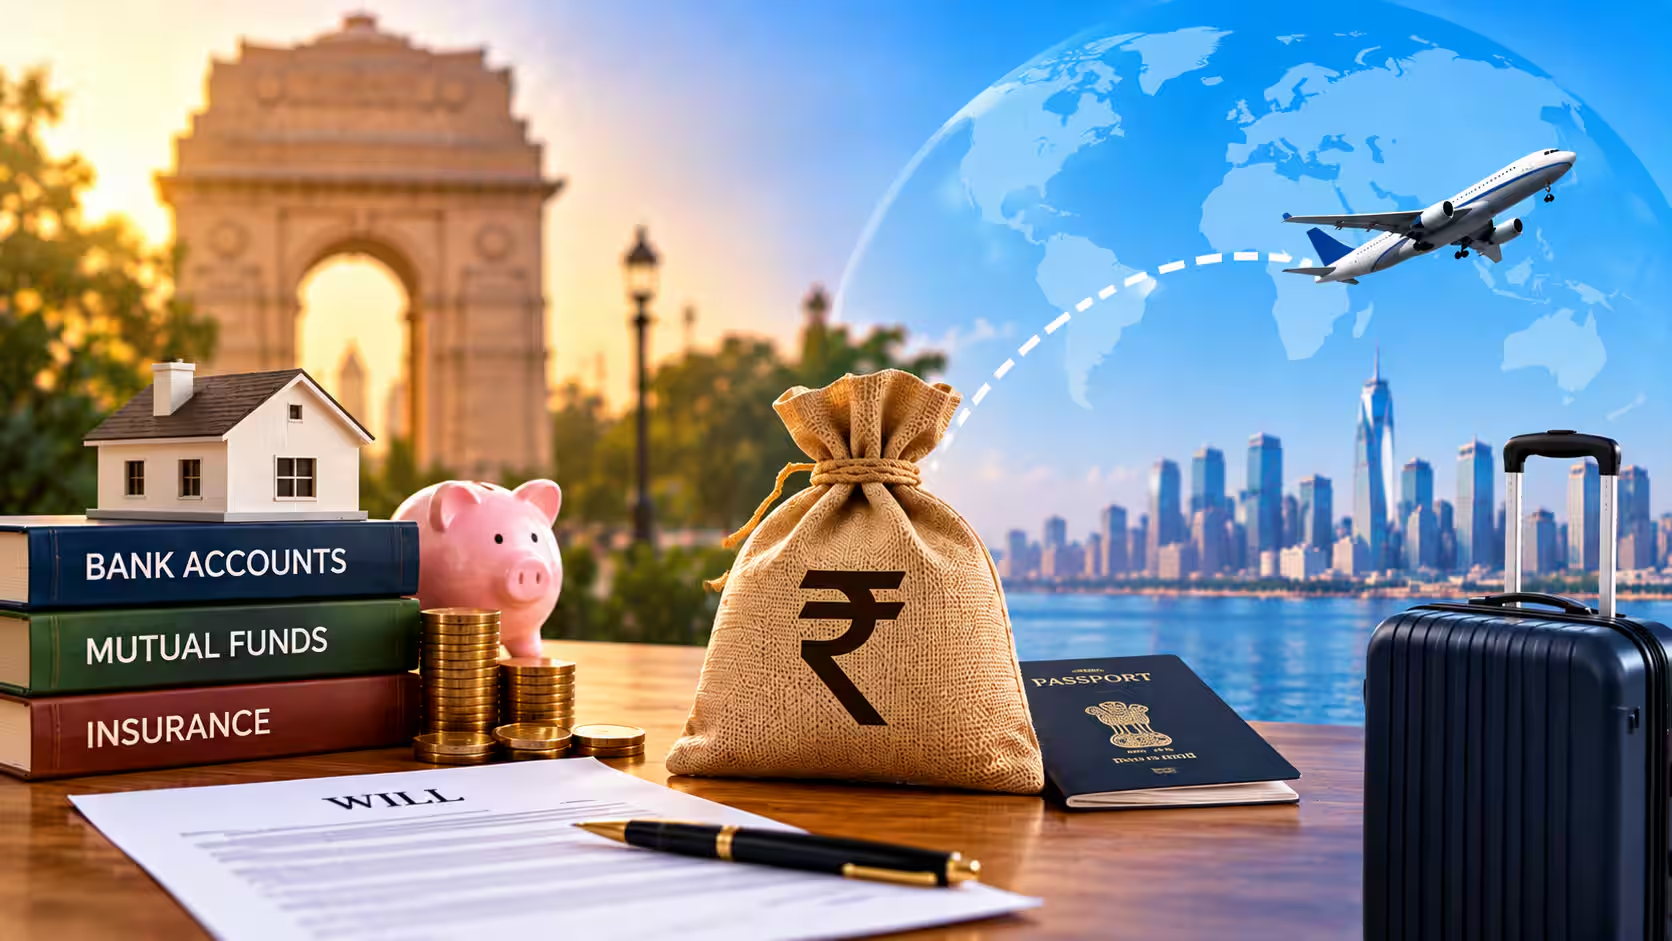
Indian investors can generally name a non-resident Indian (NRI) as a nominee to receive financial assets, such as bank accounts, mutual funds, and insurance policies, upon the asset owner’s death, but this may involve additional documentation, KYC requirements, and foreign exchange regulations.
An NRI nominee may also be able to repatriate inherited money abroad, but the process is subject to the Foreign Exchange Management Act (FEMA) and prescribed banking procedures.
Can an NRI be appointed as a nominee?
Yes. An NRI can be validly appointed as a nominee for a resident Indian’s bank deposit, mutual fund folio, or insurance policy.
Rohit Jain, Managing Partner, Singhania & Co., said, “Yes. An NRI may validly be appointed nominee for a resident Indian’s bank deposit, mutual-fund folio or insurance policy.”
According to Jain, legally, neither non-resident status nor an overseas address constitutes a general disqualification. The Reserve Bank of India’s (RBI) Master Direction on Deposits and Accounts authorises nomination for individual deposit accounts, while SEBI’s nomination framework permits nomination without imposing a residency condition.
Similarly, under Section 39 of the Insurance Act, 1938, an individual can nominate another person, including an NRI.
However, investors should understand an important distinction — being a nominee does not necessarily mean becoming the ultimate legal owner of the asset.
Jain said, “It may be understood that as per law, a nominee is only a custodian of the proceeds, and it would not override testamentary or intestate succession.”
This means nomination should not be treated as a substitute for proper estate planning or a valid Will. Investors should ensure that their nomination details and succession documents are consistent with their wishes.
Read more: Nomination is not a Will: Why legal heirs ultimately own the assets
Can an NRI nominee take the inherited money abroad?
An NRI nominee may be able to repatriate inherited money abroad, but the process is subject to the Foreign Exchange Management Act (FEMA) and prescribed banking procedures.
Jain said, “Yes, subject to FEMA.”
An NRI may route inherited rupee assets or sale-redemption proceeds through an NRO account and instruct one Authorised Dealer Category-I bank to remit up to $1 million per financial year. This can include transfer to the nominee’s NRE or SNRR (Special Non-Resident Rupee) account, subject to the required documentation.
The bank will ordinarily require documents such as the death certificate, nomination or succession evidence, asset statements, proof of inheritance and realisation, PAN and KYC documents. The nominee may also need to provide the prescribed undertaking confirming legitimate NRO receivables, along with evidence that Indian taxes have been paid or provided for.
Applicable Form 15CA, including Part D for non-chargeable remittances, and Form 15CB or an Assessing Officer certificate where statutorily required, must also be furnished.
For remittances exceeding the annual ceiling, prior RBI approval is required.
Discover the latest Business News, Sensex, and Nifty updates. Obtain Personal Finance insights, tax queries, and expert opinions on Moneycontrol or download the Moneycontrol App to stay updated!
Find the best of Al News in one place, specially curated for you every weekend.
Stay on top of the latest tech trends and biggest startup news.
Related Stories
 Global Indians
Eiffel Tower row over Hindu sect BAPS unites French politicians
5 days ago
 Global Indians
Eiffel Tower row over Hindu sect BAPS unites French politicians
5 days ago
 Global Indians
NRI sponsors non
5 days ago
 Global Indians
"Universal oneness, harmony, togetherness": Indian diaspora members laud RSS chief Mohan Bhagwat’s message in London
6 days ago
 Global Indians
Universal oneness, harmony, togetherness: Indian diaspora members laud RSS chief Mohan Bhagwat’s message in London
6 days ago
British Indian professional in race to succeed ex
6 days ago
 Global Indians
India Gets $136 Billion. Can It Win Diaspora Trust to Invest?
6 days ago
 Global Indians
Indian diaspora stage protest against RSS Chief Mohan Bhagwat's visit to British gurdwara
6 days ago