The Gulf’s female startup ecosystem is flourishing. So, where’s the funding?
Welcome to this week’s Fortune Gulf Brief. We’ll be covering:
As I reported last week, the Middle East and North Africa region’s gender funding gap remains stark, with male-founded startups accounting for more than 96% of the $375 million in capital that was deployed in August.
Female-founded startups secured just $8.5 million with a total of two transactions.
It made for puzzling reading, given that the region’s startup ecosystem, particularly in the Gulf, is thriving, with more women choosing to launch their own businesses.
Abu Dhabi alone recorded 3,058 new business licenses issued to Emirati women in the first half of 2026, highlighting the growing role of women entrepreneurs in the emirate’s economy.
So, I decided to dive deeper into the topic to gain clarity on why the disparity persists and spoke to several key players in the ecosystem to help me do so.
What quickly became apparent was the underrepresentation of women allocating capital.
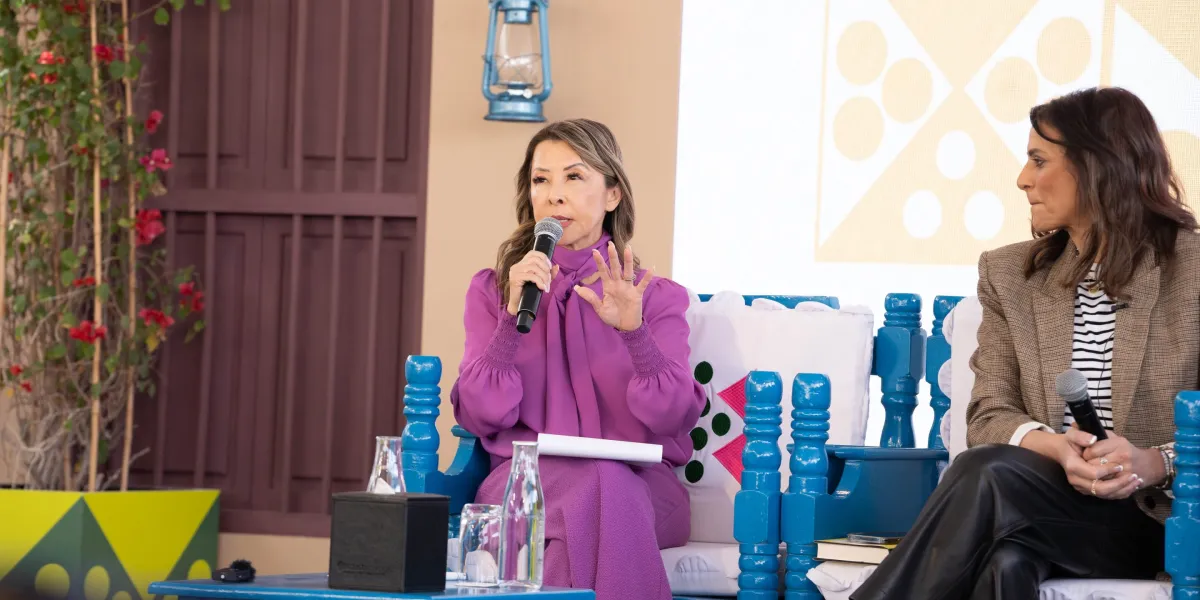
“Gulf investor networks are still very male-dominated, especially at decision-making levels,” Lucy Chow, who serves as secretary general in the UAE office of the World Business Angels Investment Forum and as a limited partner at U.K.-based Pact VC, told me.
“That matters—because deal flow follows networks.”
That’s not to say that progress isn’t being made on the ground.
In May last year, Aliph Capital, the Gulf’s first women-founded private equity firm, closed its debut fund at $200 million. Aliph Fund I will invest $15 million–$40 million in Gulf-based companies across high-growth sectors, providing capital to drive scale and operational efficiency.
In recent years, both the UAE and Saudi Arabia have been particularly proactive in making capital more accessible.
The TiE Women MENA Program 2026 marks the 7th edition of the regional initiative by TiE Dubai, which aims to mentor and fund women-led startups across the region.
The Women in Tech Accelerator, orchestrated globally by Standard Chartered and executed regionally via partners such as the UAE’s Village Capital and Saudi Arabia’s Falak Holding, has often served as the primary financial lifeline for early-stage female-led tech startups.
Last week, Standard Chartered and Falak Holding awarded three Saudi women-led start-ups equity-free grant funding totaling $45,000 at Demo Day in Riyadh.
On 28-29 September, Riyadh will host the Women Shaping Wealth Summit 2026, bringing together an influential community of investors, founders, business leaders, policymakers, and innovators.
Alongside its main-stage discussions, the summit will host a Live Demo Day connecting female founders with investors, dedicated startup and founder showcases, curated speed networking, mentorship and peer sessions, and structured opportunities for investors, entrepreneurs and leaders to forge meaningful connections.
You can read my full article here.
Melissa HancockAs ever, thanks for reading, and do keep in touch with your thoughts and ideas.melissa.hancock@fortune.com
The region’s geopolitical uncertainty appears to have done little to dent the UAE’s appeal as a place to build a long-term future among the country’s affluent residents, according to research published last week by U.K.-based wealth management firm St. James’s Place.
Its Money on the Move study, which surveyed 450 affluent and high-net-worth residents across the UAE in May 2026, found that 44% plan to retire there.
More than half said they had already stayed longer than they originally intended, while 78% expect to remain overseas for at least another eight years.
One of the most striking findings was that while 92% of respondents said they were concerned about geopolitical instability, with 46% calling it a major concern, seven in 10 said their view of the region as a place to live had actually become more positive over the past year.
The study noted that the financial upside of living in the Emirates can be significant.
A respective 96% and 97% of respondents earn and save more in the UAE than in comparable roles at home, while seven in ten believe living abroad will accelerate their retirement by at least three years.
But managing wealth across borders can be complicated. UAE expats, who account for nearly 88% of the country’s 11.4 million population, cited cross-border taxes and regulations, currency volatility, and access to investment products as among the biggest challenges to managing wealth internationally.
Abu Dhabi’s Miral will invest AED12 billion ($3.26 billion) over the next five years to expand its hospitality and theme park offerings on Yas Island—a 25-square-kilometer man-made leisure and entertainment destination. Miral is the main developer responsible for shaping and managing the Yas Island development, which is central to the emirate’s tourism drive.
The $3.26 billion investment will fund a 250-room expansion of The WB Abu Dhabi (the world's first Warner Bros.-themed hotel), as well as a brand-new lifestyle hotel.
Speaking at this year’s Arabian Travel Market event in Dubai on Monday, Miral's group CEO Mohamed Al Zaabi, said the company is targeting a roughly 35% increase in its room inventory over the next five years.
This hospitality push directly supports a planned pipeline of major attractions, including a Harry Potter-themed expansion of its Warner Bros. theme park, which is scheduled to open in 2029.
Mr. Al Zaabi said the plans will also include new rides at Ferrari World alongside a range of other new experiences.
Yas Island is already home to SeaWorld and other major amusement parks. It also hosts the Abu Dhabi Formula 1 Grand Prix.
In May last year, Miral announced a partnership with The Walt Disney Company to launch Disneyland Abu Dhabi on Yas Island, marking the first Disney theme park destination in the Middle East.
It does not yet have a confirmed opening date, but tourism officials and executives expect it to open between 2030 and 2033.
Abu Dhabi has identified tourism as a key pillar of its economic diversification.
The emirate’s 2030 Tourism Strategy plans to boost visitor numbers to 39.3 million, increase the sector's GDP contribution to AED90 billion and create 178,000 new jobs within its tourism ecosystem.
Last Thursday, the UAE pledged to invest €40 billion ($46.3 billion) in Germany in sectors ranging from AI to energy and defense as part of ongoing efforts to diversify its global trade relationships.
UAE Minister of Foreign Trade Thani Al Zeyoudi described the initial commitment as “just the beginning,” suggesting the eventual investment could be larger.
“We’re going to shop around for big opportunities to bring this relationship to the next level,” he said.
According to a statement released by the UAE’s official state news agency, the investment will enable the UAE to benefit from German expertise in areas that support the UAE's knowledge and innovation-driven economy.
Al Zeyoudi was in Germany with UAE President Sheikh Mohamed bin Zayed Al Nahyan, who was making his first official state visit to the country since 2019.
On the same day, Abu Dhabi’s International Holding Company (IHC) and India’s Adani Group inked an agreement to invest around $25 billion to develop 14 projects in the eastern Indian state of Odisha.
The agreement was signed with the government of the state of Odisha and covers a proposed portfolio spanning a range of sectors, including critical minerals and rare earths, chemicals and petrochemical derivatives, renewable energy equipment, healthcare, industrial and sports infrastructure and tourism.
In July, IHC announced it plans to invest $11.5 billion in an integrated aluminium project in Odisha through a joint venture with India's Adani Group, in what would be the country's largest foreign investment in the metals sector.
The aluminium venture further strengthens ties between IHC, chaired by Abu Dhabi Deputy Ruler Sheikh Tahnoon bin Zayed, and the conglomerate of billionaire Gautam Adani, following IHC's $2 billion investment in Adani companies in 2022.
Gulf listing volumes stand at less than $1.1 billion to date this year, according to Bloomberg, due in part to the ongoing U.S.-Iran war. That’s prompting firms, including HSBC and EFG Hermes, to pursue business in markets such as Egypt, Turkey and India. Gulf IPO markets raised $5.1 billion from 40 offerings in 2025.
Related Stories
 Business
U.S. lumber wholesaler squeezed by Trump tariffs on Canadian softwood imports
17 minutes ago
 Business
NRB entrepreneur's fintech startup raises $20 million seed round
49 minutes ago
 Business
Ministry of SMEs and Startups Creates Platform for Communication Among Startup
3 hours ago
 Business
House votes to limit Trump's power to strike Iran for 3rd time, as 7 Republicans defect
5 hours ago
 Business
Young entrepreneurs get business startup support
5 hours ago
 Business
Featured Launches Find Awards to Search 4,596 Business Awards, Rankings and Best
5 hours ago
 Business
First SMR funding agreed by European Investment Bank
7 hours ago
 Business
"They Promised 'Revitalization,' but Startup Cube Faces Repeated Water Leaks"
7 hours ago